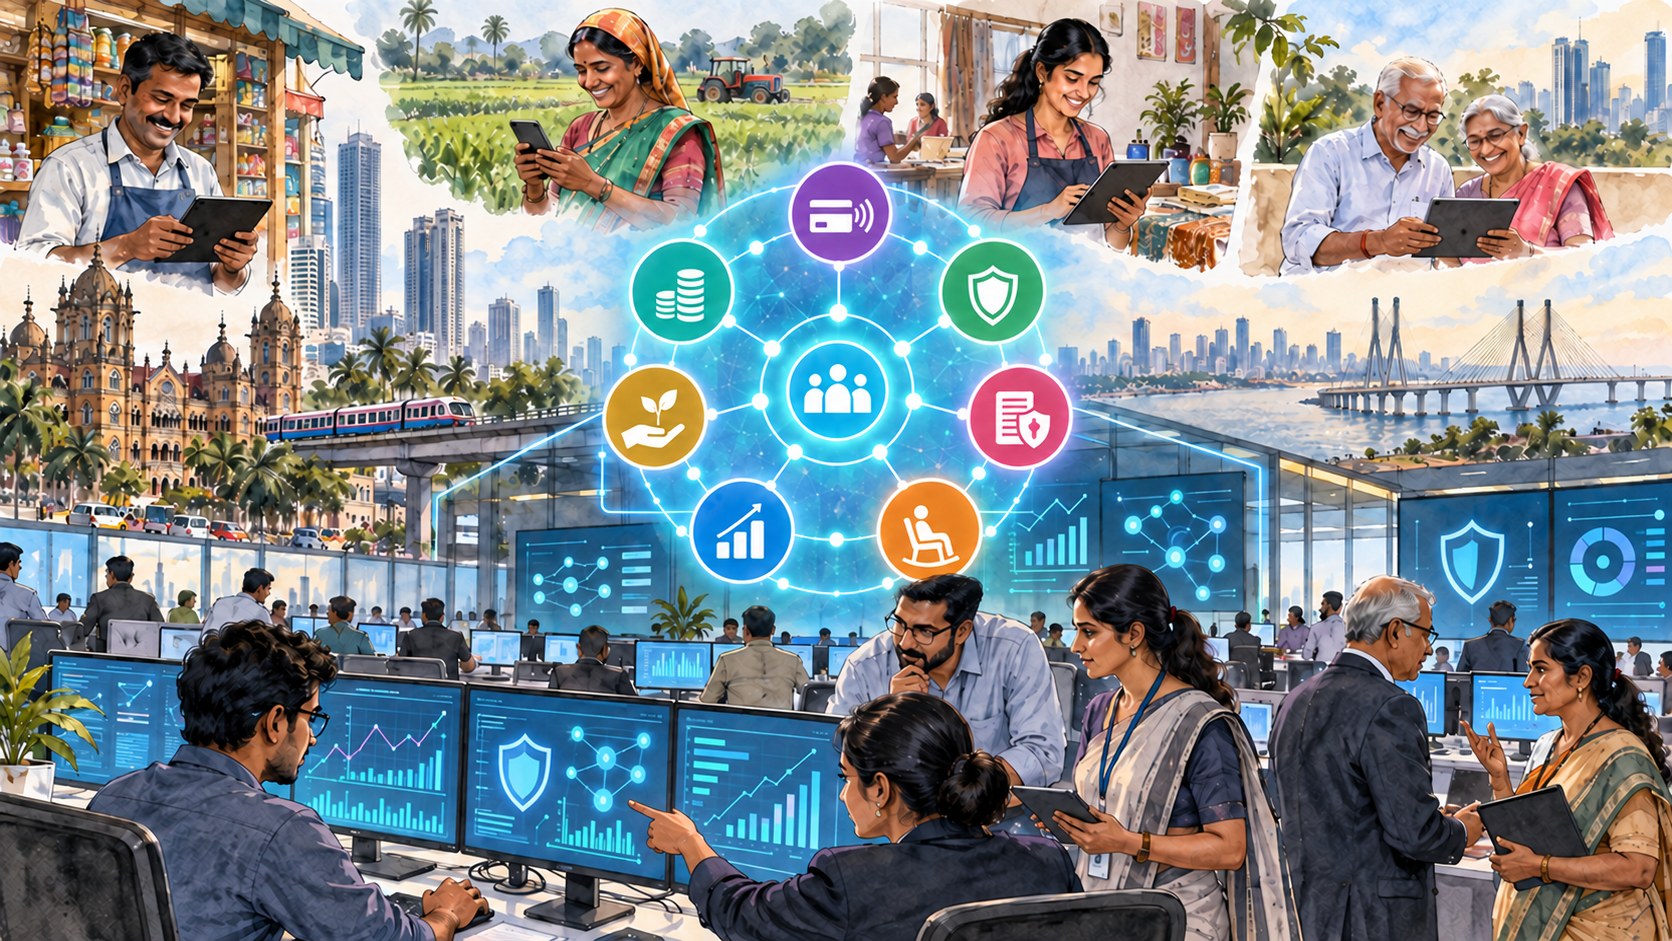
India's fintech story is often reduced to one spectacular success: the scan-and-pay simplicity of UPI. At the inauguration of Global Fintech Fest 2026 in Mumbai, Prime Minister Narendra Modi argued that the next chapter must be broader. Payments created the rails and the habit of digital participation; fintech must now widen access to credit, insurance, savings, investment and pensions while making trust the system's central design principle.
The festival, scheduled from September 8 to 11, carries the theme “Potential to Impact: Agentic AI, Tokenisation, Quantum – Trusted, Connected, Global Systems for Inclusive Finance.” According to the official summary of Modi's address, he called for an expanded global footprint for UPI, new services beyond payments, high standards of cybersecurity and ethical data protection, and stronger measurement of consumer protection. The agenda is ambitious because it asks India to retain the speed of a startup ecosystem while acquiring the reliability expected of financial infrastructure.
From payment inclusion to financial capability
A digital payment makes a transaction easier; it does not automatically make a household financially secure. A street vendor may accept UPI and still lack affordable working capital. A gig worker may receive digital income but remain uninsured. A first-time investor may access a platform without understanding risk. The next phase must convert digital footprints and low-cost distribution into useful, fairly priced products that help people withstand shocks and build assets.
This is where India's public digital infrastructure can provide leverage. Consent-based data sharing, verifiable identity and interoperable payments can reduce the cost of serving small customers. But lower distribution cost must translate into lower consumer cost, not merely higher margins or more aggressive selling. Success should be measured through appropriate credit, claim settlement, sustained savings and pension coverage, not only app downloads.
Agentic AI needs accountable limits
Agentic artificial intelligence could help a small business reconcile invoices, compare financing options or detect an unusual transaction. It could also make decisions that are difficult for a customer to understand or challenge. Financial AI therefore needs a clear chain of accountability. A regulated institution cannot outsource responsibility to an algorithm, a vendor or an opaque model.
India can lead by requiring explainable reasons for adverse decisions, human review for consequential cases, auditable model logs and strong controls on the data agents may access. Systems should be tested across languages, regions and income groups so that convenience for an urban English-speaking user does not conceal exclusion elsewhere. Innovation will move faster when builders know the rules and consumers know their remedies.
Tokenisation, quantum and the architecture of trust
Tokenisation can improve the representation and settlement of assets, but it does not eliminate the need to verify ownership, value and legal rights. Quantum technologies may eventually strengthen optimisation and reshape cryptography, but today's institutions must already prepare for migration to quantum-resistant security. These technologies should be treated as tools with staged use cases, not as slogans that outrun deployment.
Cybersecurity is more immediate. As financial services become connected, a weakness in one vendor or interface can affect millions of users. Authentication, fraud monitoring, secure software supply chains and rapid grievance resolution must grow with transaction volume. Modi's emphasis on ethical data protection recognises that trust can be lost much faster than it is built.
Taking Indian rails to the world
The globalisation of UPI can give travellers, migrants and merchants faster and cheaper payment options. Yet the goal should not be a symbolic list of international announcements. Useful expansion requires local acceptance, transparent foreign-exchange costs, dependable settlement and regulatory cooperation. India has an opportunity to offer interoperable digital infrastructure as a practical partnership, especially to countries seeking inclusion without dependence on a handful of private networks.
The official programme note for GFF 2026 framed the event around trusted and connected systems. That order matters. Global scale without consumer trust would magnify failure; trusted systems can make scale sustainable.
The standard for the next decade
India's fintech ecosystem has already demonstrated that population-scale innovation is possible. The next test is harder: can it deliver personalised services without predatory design, use advanced AI without unaccountable decisions and expand data use without weakening privacy? Can it serve citizens who have modest balances, intermittent income or limited digital literacy as thoughtfully as premium customers?
Modi's GFF agenda points in the right direction because it moves the conversation from transaction count to financial outcomes. UPI proved that India could build a powerful digital rail. The next decade must prove that credit, insurance, savings, investment and pensions can travel on that rail securely, fairly and at global scale.