Current affairs · Pro-development analysis · 12 October 2026
The GST Council’s October recommendations target registration, refunds, appeals and compliance, extending the government’s effort to make tax administration more predictable and trust-based.
A reform agenda focused on everyday compliance
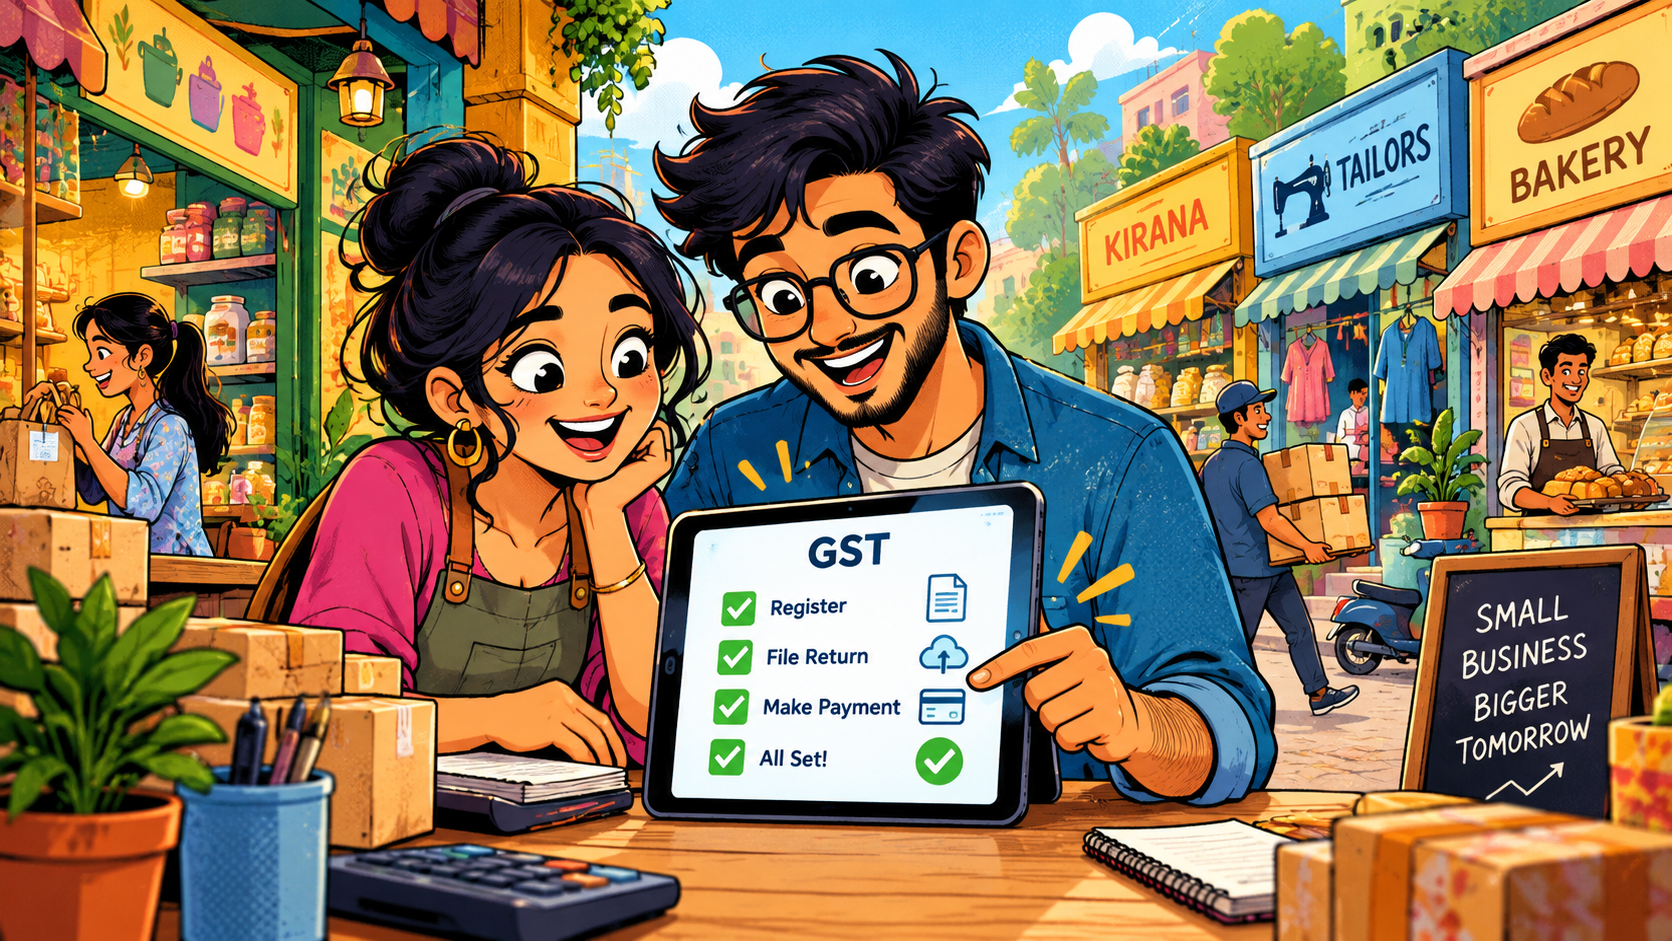
India’s latest GST reform discussion turns attention from tax rates to the experience of using the system. At its 57th meeting on 8 October, the GST Council recommended changes across registration, returns, refunds, adjudication and trade facilitation. The aim is straightforward: reduce avoidable friction so that firms can spend more time serving customers and less time navigating procedures. Source 1
This direction builds on the wider GST reform process. A common national tax framework already gives businesses a shared structure for interstate trade. The next improvement is making that structure easier to understand and more predictable in practice. For a small manufacturer or service provider, a clear registration checklist and timely answer from the portal can matter as much as a headline tax change.
The Council’s recommendations cover clearer guidelines for registration applications, better application forms and a more user-friendly portal. Such practical measures can help first-time entrepreneurs and small firms that do not have a large in-house tax team. When requirements are visible and decisions arrive on time, businesses can plan hiring, procurement and sales with greater confidence.
For new businesses, the first interaction with the tax system can shape their confidence in formalisation. A simpler registration journey and plain-language guidance can lower that initial barrier. This supports a wider goal of bringing more enterprises into a transparent national market, where firms can grow beyond local limits and participate in larger supply chains.
Greater trust, clearer rules
Among the recommendations are removing arrest provisions under GST, raising the prosecution threshold from ₹1 crore to ₹5 crore and reducing the maximum general penalty from ₹25,000 to ₹10,000. The Council also recommended a cap on certain pre-deposits in cases involving only a penalty and no tax demand. These proposals signal a shift toward proportionate enforcement and easier access to appeals. Source 1
A trust-based system still needs firm action against deliberate evasion. The objective is to distinguish serious wrongdoing from procedural mistakes and to make the consequences more proportionate. Clearer notices, consistent standards and a defined path to challenge an order can give honest taxpayers more confidence that they will be treated fairly.
The Council also recommended common standards for GST notices and proceedings. Uniform communication can help taxpayers understand what is being asked, which records are relevant and how to respond. This reduces confusion for businesses operating across states and supports officials by making cases easier to process consistently.
Proportionate enforcement is also important for the credibility of a reform. When rules distinguish between a genuine mistake and deliberate concealment, taxpayers are more likely to view compliance as fair. A predictable system benefits both sides: businesses understand their duties, and administrators can concentrate attention on cases that merit closer scrutiny.
Refunds and working capital
Refund-related recommendations are especially important for exporters and businesses whose input tax credit accumulates. The Council proposed wider eligibility for input tax credit and refunds, including specified situations involving capital goods and input services. It also recommended faster refunds to improve working capital. For a small enterprise, a refund received on time can help pay suppliers, wages and operating costs without taking on additional borrowing. Source 1
The government’s emphasis on automated and faster decisions points toward a tax administration that uses digital systems to reduce routine delays. Automation is most useful when it is paired with clear explanations and a way to resolve genuine exceptions. A business should be able to see the status of a claim and understand what action, if any, is required from it.
The Council also recommended simplified GST registration for small sellers on e-commerce platforms and measures to facilitate exports of services. These changes could make formal market access easier for home-grown brands, independent service providers and small firms that want to sell beyond their immediate locality. Digital commerce has widened opportunity; straightforward compliance can help more businesses take part.
Faster refunds can be especially useful during a period of expansion, when firms are buying equipment or adding capacity. Access to working capital affects a business’s ability to fulfil orders and pay suppliers on schedule. Reducing avoidable waiting can therefore improve the practical value of the tax credit system for productive enterprises.
Cooperative federalism and the road ahead
GST Council decisions are shaped through a forum that brings the Union and states together. That cooperative model allows governments to discuss how rules affect different regions and sectors before decisions are taken. It is one reason process improvements can be designed with both national consistency and the day-to-day realities of state administrations in view.
The Council’s recommendations still need the relevant legal amendments, notifications and implementation guidance. That next stage will determine when each measure takes effect and how taxpayers should use it. Businesses should follow official notifications and FAQs as they are issued, rather than assume every recommendation is already operational. Source 1
The policy direction is encouraging for India’s entrepreneurs. Less paperwork, proportionate penalties, more predictable refunds and clearer proceedings can improve confidence in the formal economy. If implementation is timely and the portal works reliably, the October GST recommendations can turn the promise of a simpler tax system into a tangible everyday benefit. The government’s focus on trust, speed and lower compliance costs is a constructive step in that journey. Source 2
Implementation will require close coordination between the Union, states and tax officials at every level. Guidance should be published in accessible language, and businesses should have time to adapt to changes. With consistent administration and responsive support, the reform agenda can strengthen trust and make compliance a more routine part of doing business.